BUYERS
OUR FOCUS
OUR NEIGHBORHOODS
Contact
- 34 South St Jamaica Plain, MA 02130
- 6176764082
- info@focusre.com
How Rising Mortgage Rates Impact Your Homebuying Power
Mortgage interest rates can have a major impact on how much home a buyer can comfortably afford. Even a seemingly small increase in rates can significantly change monthly payments—and ultimately reduce a buyer’s purchasing power.
Let’s look at what happens when mortgage rates increase from 6% to 7.5%, assuming a 30-year fixed mortgage with 20% down.
What Happens to the Monthly Payment?
Consider two common purchase prices: $500,000 and $1,000,000.
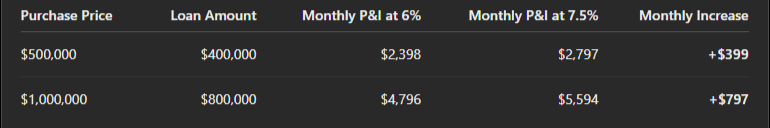
The increase from 6% to 7.5% results in approximately a 16.6% increase in the principal-and-interest payment.
For a $500,000 home, that means paying about $399 more per month. For a $1 million home, the difference is nearly $800 more every month.
What Does This Mean for Purchasing Power?
The bigger question for many buyers isn't simply, "How much higher will my payment be?" It's:
"How much less house can I afford?"
If a buyer wants to maintain approximately the same monthly mortgage payment, a rate increase from 6% to 7.5% reduces purchasing power by roughly 14.3%.
For example:
-
A buyer who could afford a $500,000 home at 6% could afford approximately $429,000 at 7.5%—about $71,000 less purchasing power.
-
A buyer who could afford a $1,000,000 home at 6% could afford approximately $857,000 at 7.5%—about $143,000 less purchasing power.
That is a significant difference, especially in competitive markets where buyers are already working with tight budgets.
Why Interest Rates Matter So Much
When rates rise, buyers don't necessarily have to abandon their home search. Instead, they may need to adjust their expectations.
A higher mortgage rate can mean:
-
Looking at a lower purchase price
-
Increasing the down payment
-
Choosing a different neighborhood
-
Considering a smaller home or condo
-
Waiting for rates to potentially improve
-
Exploring different financing strategies
This is why understanding your monthly payment—not just the purchase price—is so important when you're buying a home.
The Bottom Line
As a useful real-estate rule of thumb, moving from a 6% mortgage rate to 7.5% can reduce purchasing power by roughly 14%, assuming the buyer is primarily limited by their monthly mortgage payment and other factors remain unchanged.
Of course, the actual numbers will vary. Property taxes, homeowners insurance, condo fees, PMI, loan type, and down payment can all affect a buyer's total monthly housing cost.
If you're thinking about buying, it's worth looking beyond the headline interest rate and understanding how different financing scenarios affect your overall budget.
In a changing market, knowing your numbers can help you make smarter decisions and focus on the homes that truly fit your budget.